Accountable Reimbursement Plans for Churches: Tracking Ministry Expenses the IRS Way
An accountable plan needs a business connection, timely substantiation, and return of excess advances. Here is how a church can organize reimbursements under current IRS guidance.
Alex Chen
Product Manager & Personal Finance Advocate
Accountable Reimbursement Plans for Churches: Tracking Ministry Expenses the IRS Way
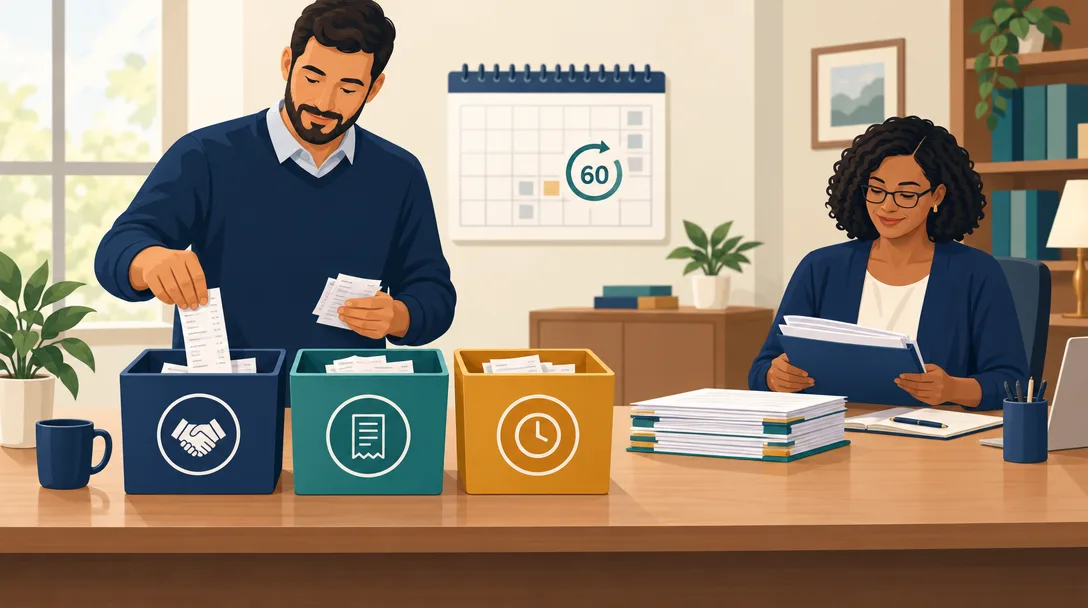
An accountable reimbursement plan needs a business connection, adequate records, and a reasonable process to return excess advances. The IRS treats 60 days to substantiate expenses and 120 days to return excess as safe-harbor periods; they are not universal hard deadlines. A church should document its policy and ask a tax professional how the rules apply to its facts.
Key takeaways
- An accountable plan requires a business connection, adequate substantiation, and a reasonable process to return excess advances.
- IRS safe-harbor periods include 60 days to substantiate and 120 days to return excess; facts and circumstances still matter outside those periods.
- The $75 documentary-evidence exception does not remove the need to keep adequate records, and lodging has separate documentation rules.
- A written policy and consistent review process can help a church keep organized records; they do not guarantee a particular tax result.
- Yomio Business Mode can help collect receipt records and export expense data as CSV; it does not provide tax or compliance approval.
The three core requirements of an accountable plan
The IRS describes the accountable-plan requirements in Publication 15 and Treasury Regulation 26 CFR § 1.62-2. Amounts that meet the rules are generally excluded from wages and Form W-2. Amounts that do not meet them may be treated as nonaccountable-plan wages; an arrangement can have separate accountable and nonaccountable parts.
1. Business connection requirement
An expense needs a business connection to the church's activities. Examples may include Sunday school materials, building repairs, conference registration, or mileage for a ministry visit. Personal costs do not become business expenses because a church pays for them; ask a tax professional about mixed-use or unusual items.
The church should document its reimbursement process and communicate which expenses and records it accepts. A short written policy can help staff follow the same process, but the policy alone does not establish that every reimbursement meets IRS rules.
2. Substantiation requirement—records and reasonable timing
Employees must adequately account for expenses within a reasonable period. IRS Publication 463 says substantiation within 60 days after an expense is paid or incurred is treated as occurring within a reasonable period under its safe harbor. The general rule depends on the facts and circumstances, so 60 days is not a universal cutoff.
Receipts: IRS rules generally require documentary evidence for lodging regardless of amount. Some other expenses under $75 may qualify for an exception from documentary evidence, but the employee must still substantiate the expense with adequate records, including amount, date, place, and business purpose where required. Check IRS Publication 463 for the applicable rules.
Timing: If a pastor incurs an expense on January 15 and submits it within 60 days, the submission is within the safe harbor. A later submission falls outside that safe harbor, but that fact alone does not decide the tax treatment. The church should apply its policy and obtain tax advice when a submission is late or incomplete.
Form of documentation: Keep records that show the amount, date, place, and business purpose. The right evidence depends on the expense and applicable substantiation rules; a receipt alone may not establish why the purchase served the church.
3. Return of excess requirement
If the church pays an advance or allowance, the employee must return any excess within a reasonable period. IRS Publication 463 treats return within 120 days after the expense was paid or incurred as a safe harbor. This is not permission to wait until year-end in every case; use a process that fits the timing and circumstances of the expenses.
The practical framework: running an accountable plan without a finance department
Even a small church can organize an expense-reimbursement process. The tax rules focus on the arrangement's business connection, substantiation, and return of excess; a written policy and repeatable review cycle can help document and administer that process. The IRS does not prescribe a particular software tool or policy format.
Step 1: Document the accountable-plan process
Ask the church's board or other authorized body how to adopt or document its process. A memo or board resolution may help, but the church should confirm its governance and tax requirements. Consider professional advice for complex arrangements. Document topics such as:
- Who can submit: Pastors, staff, volunteer leaders (anyone incurring ministry expenses on the church's behalf).
- What qualifies: Expenses with a direct ministry connection (give examples: Sunday school supplies, building repairs, mileage to home visits, conference registration, emergency pastoral assistance).
- When to submit: Set a clear submission period and review late claims under the facts-and-circumstances standard. The IRS 60-day period is a safe harbor, not a universal deadline.
- What to include: Receipt or invoice, date of expense, amount, and a brief note on the ministry purpose (e.g., "Office supplies for worship team").
- Approval: Who reviews and approves (typically the treasurer or finance committee).
- Return of excess: Set a process for returning excess advances. IRS guidance treats a return within 120 days as a safe harbor, not a universal hard deadline.
Circulate the policy to staff and keep a copy with the church's records. Have a qualified tax professional review it before relying on it for federal tax treatment.
Step 2: Set up a monthly submission and review cycle
Week 1 of each month: Distribute a simple form (email or printed) reminding staff to submit expenses from the previous month. Include a checklist: date, amount, receipt, ministry purpose.
Week 2: Review submissions. Are the records adequate for the expense? Was it submitted within the policy period? Does the purpose align with the policy? If not, ask for clarification and assess the facts before deciding how to handle it.
Week 3–4: Post approved reimbursements to the general ledger and cut checks. Keep copies of receipts and documentation in a folder (physical or digital) organized by month and staff member.
Quarterly: Review a summary of submitted expenses and reimbursements against the policy. Keep the report with the underlying receipts and records.
Step 3: Use receipts as your anchor—but make it easy
If your pastor is scanning receipts by phone and emailing them, great. If she's keeping a shoebox, you'll have problems. The best churches combine:
- A clear timing reminder: State the plan's submission process and explain that the IRS safe harbor for substantiation is 60 days, while late claims need individual review.
- A receipt repository: A shared folder (Google Drive, Dropbox, email archive) organized by staff member and month.
- A log: A simple spreadsheet with columns for date, staff member, amount, receipt status ("yes" or "missing"), and approval date. This is your checklist.
Step 4: Audit for the most common mistakes
Once a quarter (or more often for a larger church), scan your reimbursement log for:
- Late submissions: Claims submitted after the church's target or the IRS safe harbor. Request supporting records and consult a tax professional about the facts before deciding how to report the payment.
- Missing records: If a record is incomplete, ask for additional support. Apply the documentary-evidence exception only where it fits; it does not remove the requirement to substantiate the expense.
- Vague purposes: If a receipt says "Office Max $42" but doesn't clarify what was bought, send a quick email asking for a note on what it was for. Document the reply.
- Advance overpayments: If you gave a staff member a $500 advance for a conference and the conference cost $380, make sure the $120 overpayment is returned and posted before year-end.
Tip
Keep the date an expense was incurred and the date it was submitted when your process can capture them. Those details can help you apply the IRS safe harbor and review late submissions.
Common accountable-plan recordkeeping problems
Mistake 1: Unclear process—"We've always done it this way." The IRS evaluates whether the reimbursement arrangement meets the accountable-plan requirements; a written policy alone does not decide the result. Without clear instructions, staff may submit incomplete or late records. Fix: Document the process and ask a qualified tax professional to review it. A policy does not replace the required business connection, substantiation, and return of excess.
Mistake 2: Treating the 60-day safe harbor as a universal cutoff. A claim submitted after the safe-harbor period needs review; timing alone does not settle the tax treatment. Fix: Request the records, document the decision, and get tax advice when the plan's requirements may not have been met.
Mistake 3: Assuming the $75 rule removes recordkeeping duties. Some expenses under $75 may not require documentary evidence, but the employee still needs adequate records, and lodging has separate rules. Fix: Keep an expense record with the details required for its type, even when a receipt exception applies.
Mistake 4: No documentation of the business purpose. A receipt that says "Visa charge $82.15" tells you how much was spent but not why. The IRS wants to know: "church building supplies," "pastoral training materials," or "mileage to hospital visit." Fix: Create a simple form or email template with fields for date, amount, receipt, and purpose. Make staff fill it out as they submit.
Mistake 5: Mixing personal and ministry expenses. A pastor buys a $200 laptop that will be used partly for church administration and partly for personal use. If you reimburse the full $200 as a ministry expense without apportioning, the IRS can challenge the whole amount. Fix: For shared-use items, reimburse only the documented ministry portion. Have staff estimate or document the split.
Mistake 6: No process for returning overpayments. The church pays a staff member $500 for a conference and the actual cost is $350. The $150 excess should be returned under the plan's process. The IRS treats return within 120 days as a safe harbor; determine the tax treatment based on the full facts if it is returned later. Fix: Track advances and reconcile them promptly, with written follow-up for any balance.
Run an accountable plan your church can actually follow
Yomio Business Mode helps teams submit receipt records for review and export expense data as CSV. Keep the church's written policy, cash records, and tax review in the processes that apply to your organization.
See Business Mode