Why Budgets Fail: Five Common Problems and Practical Fixes
Review five common budgeting problems, compare limits with actual spending, include irregular costs, and choose practical changes that fit your situation.
Yulia Lit
Consumer Psychology & Behavioral Economics Researcher
Why Budgets Fail: Five Common Problems and Practical Fixes
When a budget repeatedly breaks, compare it with actual spending, add irregular costs, and check progress during the month. These steps can show whether the limits, timing, or tracking method need to change; missing a target does not mean you have failed.
This guide covers five common planning problems and practical ways to adjust them. The examples are prompts for review, not research-backed guarantees about how much a particular change will save.
Key Takeaways
- A missed budget target is information you can use to review the plan
- Compare limits with recent spending instead of setting targets from guesswork
- Add predictable, non-monthly costs to the plan
- Automation can make some recurring steps easier, but it does not replace reviewing the plan
- Recording expenses and setting a budget are separate steps
Reason 1: The Budget Is Built on Hopes, Not Data
One common problem is setting limits from what you hope to spend rather than what you currently spend. Use your own recent statements to make a starting plan, then choose one category to adjust at a time.
For example, if a household spends about £485 a month on groceries, a first-month target of £300 may be unrealistic. The gap is a signal to review the data and set a gradual change.
If actual spending is already £400 by the 20th, a £300 monthly limit does not describe your current pattern. Adjust the target or decide which specific purchases you will change.
The fix: Before setting a limit, review recent spending for a period that reflects your pay and bill cycle. Use it as a starting point, then make any planned reduction specific and realistic.
Warning
If recent grocery spending is about £485 and you set a £300 limit, the plan assumes a £185 change. Check what would need to change before relying on the lower number. A limit works as a plan only when it reflects both your records and a step you intend to take.
Reason 2: Irregular Expenses Are Completely Ignored
Some plans list regular monthly bills but leave annual or occasional costs out. Examples can include car service, insurance renewals, gifts, dental care, or work travel.
Some of these costs can be anticipated even though they do not arrive monthly. A basic monthly template may not include them unless you add a category or other plan for irregular expenses.
If a non-monthly expense was not included in the plan, it may require you to revise that period's allocations. A plan for expected irregular costs can make those amounts easier to review.
In the Federal Reserve's 2025 household survey, 63% of adults said they would cover a hypothetical $400 emergency expense exclusively with cash, savings, or a credit card paid off at the next statement (report). This describes a survey response, not an individual household's ability to handle every emergency.
The fix: List irregular expenses you reasonably expect in the next 12 months. Estimate their total and divide by 12 if a monthly set-aside fits your cash flow. Keep the amount in a separate category or account if that helps you plan for those costs.
Tip
Give each planned set-aside a clear name, such as “car service” or “annual insurance.” Use a separate account or category if that makes it easier to see which amount you have reserved for each cost.
Reason 3: The Budget Requires Too Many Decisions
If you must make a new decision for every purchase, following the plan can take more effort. Use reminders, recurring transfers, or clear category limits to make routine choices easier to review.
The fix: Consider repeatable steps for decisions you make often. For example:
- An automatic savings transfer on payday (before you see the money)
- Automatic bill payments where the due dates and available account balance make that appropriate
- Automatic credit-card payments if you can keep enough funds available for the payment
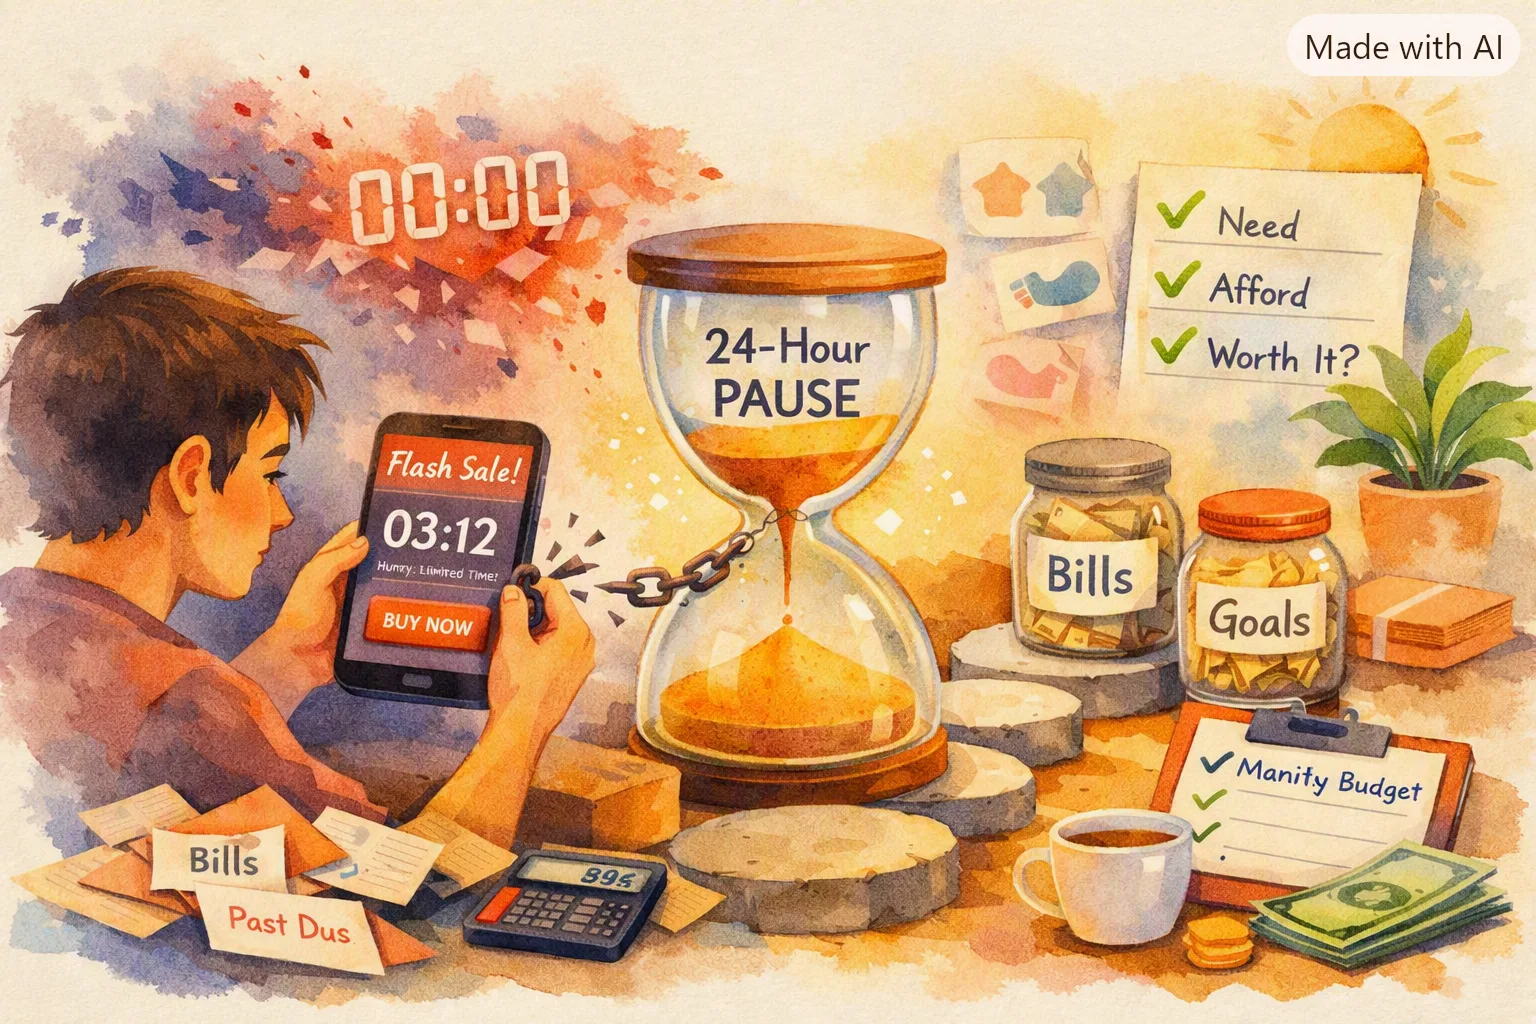
- For an optional purchase, set a pause rule that fits your budget, such as waiting before buying a higher-cost item
Choose a few repeatable steps that reduce the number of choices you need to make each time you review the plan.
Diagnosis
Which Budget Failure Modes Apply to You?
Select every statement that sounds familiar. Then get targeted fixes.
Reason 4: There Is No Feedback Loop
A budget without tracking is a plan without a way to compare it with actual spending. If you check only at month end, you may have fewer opportunities to adjust spending during that period.
This is the distinction between budgeting (setting limits in advance) and expense tracking (recording what you actually spent). They are separate activities, and you need both. A budget without tracking is wishful thinking. Tracking without a budget is data without direction.
Reviewing expenses during the month gives you time to change a plan before the next billing cycle. The size of any effect depends on your circumstances and how you use the information.
The fix: Choose a review schedule that fits your spending and pay cycle. If you compare recorded spending with your plan during the month, you may have more time to decide whether to adjust upcoming choices; a month-end review can still help you plan the next period.
Information
There is no single review frequency that fits every budget. A weekly check may work for frequent purchases, while a monthly review may suit fixed costs. Use the shortest schedule that gives you useful information without adding more work than you can maintain.
Reason 5: The Plan Leaves No Room to Revise
Some people find a rigid plan difficult to use when expenses or priorities change.
If every difference from the plan feels like failure, it can be harder to review what happened and choose a useful adjustment. A £200 dining estimate and a £235 total may call for a change to the next estimate, a spending choice, or another part of the plan.
One missed limit does not make the rest of the plan useless. Record what happened, decide whether the expense was predictable, and revise the plan if needed.
The fix: Decide in advance how you want to handle changes. Options include:
-
A buffer category: Choose an amount that fits your budget for costs that do not fit another category. When you use it, update the plan to reflect what happened.
-
A review range that fits your budget: Decide when you want to check a category and what action you will take if spending is higher than planned.
-
A regular reset: Review the previous period, record what changed, and revise the next plan where needed.
Success
Costs and priorities can change. When actual spending differs from a limit, record why and decide whether to keep the limit, adjust it, or change a specific choice next period.
Which Budget Failure Is Yours?
The five planning problems can overlap. Use the examples to choose one part of your budget to review first.
Use the diagnosis below to identify a likely problem, then try one change first so you can see whether it helps. Add other changes when they fit your routine.
| Primary Symptom | Most Likely Failure Mode | Priority Fix |
|---|---|---|
| Budget is above its limit early in the month | Aspirational limits | Review recent data and planned changes |
| Works fine until something unexpected hits | No sinking funds | Create irregular expense fund this week |
| Following the plan requires many decisions | Too many decisions | Try a repeatable step for a common task |
| Little awareness of spending until month end | No feedback loop | Choose a spending-review schedule |
| One slip leads to "forget it, I'll restart next month" | Zero-tolerance design | Add a buffer category; adopt a monthly-reset rule |
The Budget That Is Hardest to Kill
A budget designed to survive contact with real life has these properties:
- Limits informed by recent records and current priorities
- Sinking funds for every predictable irregular cost
- Repeatable steps for savings and fixed bills where they fit
- A regular spending review that fits your pay and bill cycle
- Room to revise the plan when costs or priorities change
The goal is a plan that remains useful as your costs and priorities change.
Expense records help you check a budget against what you recorded. Receipt details may show item-level information, while other statements may show merchant and transaction totals; compare the sources you have and note any gaps. Learn more ways to track spending.
Build a budget from your actual spending, not guesswork
Scan receipts or enter expenses manually, review the extracted details, and compare the records you add with your own budget plan. Yomio does not capture every purchase automatically or create a budget for you.
Start tracking freeFrequently Asked Questions
I have tried budgeting multiple times and always quit. What makes this time different? Think about which part of the earlier plan did not fit. If the limits ignored actual costs, use recent records to update them; if the process involved too many decisions, try a repeatable step. Choose an approach you can maintain.
Should I use a budgeting app or a spreadsheet? Choose a format you can update and review. Compare how each handles the records, categories, calculations, and sharing you need, then use the one that fits your routine.
What if I keep overspending in the same category every month? Review the expenses and the reason they exceed the plan. Your recent total may show that the limit needs to change; if you want to spend less, name the choice you plan to change and review whether it worked.
My income is inconsistent. Can I still budget? Yes. Build your base budget on the lowest reliable income you expect, then assign extra income after it arrives to priorities such as bills, savings, or debt.